
A 12-year-old people analytics consultancy tore up the software it spent five years building, rebuilt it AI-native in six months, and landed on a thesis that should worry every legacy analytics vendor and reassure every services firm sitting on unmonetized expertise: the moat was never the technology.
For months, I’ve been tracking a shift in how value gets created in HR tech as AI adoption continues to rise: service and expertise, not the software wrapped around them, are becoming the biggest differentiator. And analytics may be the clearest example of that shift happening right now, in real time, in front of buyers.
I sat down with Joelle Emerson, Co-founder and CEO of Paradigm, for a briefing on Surface, the company’s AI-native people intelligence platform, and the conversation crystallized something I’ve been watching build for months: when AI makes building software nearly free, what’s actually scarce is judgment earned the hard way.
Paradigm’s answer is not a new algorithm. It’s twelve years of having done the work.
The Kleenex Moment
Six months ago, Joelle looked at what her team had built (a learning platform launched in 2020, an analytics layer bolted on in 2021) and made the call that most consulting shops-turned-software companies never make. Stop patching. Throw it away.
“We’re not the Titanic,” she told me. “We’re a small company. Let’s instead just throw away what we’ve built and build something AI-native.”
I’ve heard Jim Collins tell the story of Kleenex’s founders shutting down every other paper mill they owned to bet everything on one product (Kleenex). It’s framed as visionary in hindsight and felt like a brawl in the room at the time. Paradigm’s version of that decision, burning a working platform to rebuild AI-native in six months, is the same trade, made faster and with a lot less runway to be wrong. Most consulting and services firms that build technology never get to that decision. The failure mode I actually see there isn’t bolting AI onto old code; that’s a legacy SaaS problem. It’s staying services-first indefinitely: building just enough platform to look credible in a pitch, never making the harder shift to being a true tech company with a product customers would buy on its own. Paradigm didn’t take that route either. They launched Surface, and at the time of our conversation, roughly 70 of their existing clients had already migrated to it, paying what they were paying for something Joelle says is “way better than what you were using before.”
That’s the headline. Here’s why it matters more than another product launch.
The Moat Just Moved
For a decade, Paradigm sold judgment by the hour: go into a company, look at the data, and tell leadership what to do about attrition, performance, culture, etc. High-margin, high-trust, completely un-scalable. The constraint was never insight. Paradigm has run this playbook with roughly 2,000 companies. The constraint was that only a person could hold the judgment, and a person can only bill so many hours.
Surface is Paradigm’s bet that AI collapses that constraint without collapsing the thing that made the judgment good in the first place. And what made it good was never proprietary software. It was two things nobody can spin up in a weekend: the pattern library from 2,000 client engagements, and what Paradigm calls its Talent Practices Inventory, a structured onboarding process that captures the stuff that never shows up in an HRIS. Why the founder won’t approve a policy everyone else uses. Which past interventions actually moved the needle, and which ones looked good in a deck and did nothing?
Joelle’s framing, almost verbatim: “AI is really only as good as the context you feed it.” ChatGPT has too little context and needs to be re-prompted every time. Enterprise copilots deployed across a whole company often have too much, most of it irrelevant to the question being asked. The context that actually produces good judgment (what’s normal at a Fortune 500 company versus a fast-growing startup, what a specific team has already tried and rejected) isn’t written down anywhere. It lives in twelve years of consulting engagements, and Paradigm is the only provider I’ve spoken to that has it.
That is the moat. Not the model. Not the UI. The 2,000-company pattern library and the mechanism for feeding it context that a generic LLM will never have on its own.
Service-as-Software, Not Software-with-a-Chatbot
The tell isn’t the product. It’s what Paradigm did to its own business model.
Joelle described the shift plainly: natural attrition on the services team, no backfill, and a live internal debate every time a $10,000 consulting engagement shows up on the table: take the billable work, or put the same hours into making the agent good enough that the client never asks for a consultant again. “Consulting revenue, she told me, ‘is such a slog, you have to go after it again and again and again.’ Building a product ‘that people love and want to use,’ by contrast, means ‘it’s very pleasant to not have to do that.'”
That’s a founder choosing to cannibalize her own highest-margin line of business, on purpose, because she’s betting the platform is worth more than the hours. I flagged something similar to her from a talent acquisition client I advise: fully-built-out, all-service shops used to have the hardest positioning problem in the market: too much service, not enough software story. That story just inverted. Now the pitch writes itself: we’ll come in and guide you with the technology, or hand you the technology and be on call when you need us. What used to sound like hedging now sounds like exactly the on-ramp a buyer who is simultaneously pushed to act on AI and stuck on which vendor to trust actually wants.
Where This Sits in the Hourglass
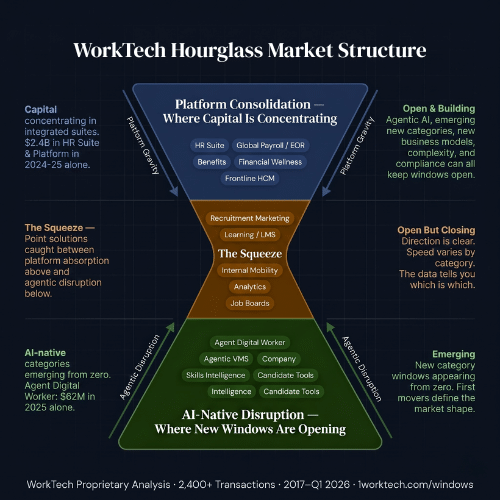
If you’re following our Market Windows Series, you know how I map this market right now: an hourglass. At the top, the platforms across all HR and Work Tech categories are absorbing capability through their own agent suites and acquisitions, moving fast, but time will tell who moves fast enough to escape a much slower, wider window closing under them. At the bottom, AI-native startups with no legacy code, no legacy pricing, and business models built for consumption from day one. In the middle, everyone who came to market more than 24 months ago and hasn’t made the shift is getting squeezed from both directions at once.
a16z published a piece the same week I met with Joelle, arguing one of those platforms, Workday, is due for its own PeopleSoft moment: that Workday was PeopleSoft rebuilt for the cloud, AI is the next platform shift, and the company charging customers extra for AI features instead of building it in is not the company that survives that shift. I don’t fully buy the “Workday is dead” framing. The top of the hourglass has a much wider, slower-closing window than the piece gives it credit for. But the underlying point about pricing power is right, and it’s the same one Joelle made about Paradigm’s former position: a vendor that has to protect a legacy tech stack can’t chase the price point AI-native competitors set. Paradigm’s whole rebuild was a bet that they’d rather be the disruptor than get disrupted waiting to defend one.
Paradigm doesn’t fit neatly in that hourglass, and that’s the point. It has the pattern library and client base of a top-of-the-glass incumbent and the cost structure and shipping speed of a bottom-of-the-glass native. That combination is rare enough that I don’t have a clean second example to point to yet.
It also lands squarely within a category that WorkTech’s own data currently marks as Open But Closing: Analytics. The standalone analytics vendors, the Visier-generation platforms, carry the tech stack, the price point, and the go-to-market of a category that peaked years ago, and they’re increasingly competing not against each other but against a line item on a platform renewal. Joelle’s read on her own market, unprompted, matched that framework almost exactly: legacy analytics players “don’t tell you what to do,” carry a large tech stack that “means they have to continue to be expensive,” and have few options to move on price. That is a closing-window vendor describing its own category, correctly, from the inside.
What keeps Analytics from closing outright, what makes it Open But Closing rather than simply Closed, is the same exception I flagged in the last Market Windows piece in the series: the outcome-connected layer that ties experience and performance data together and actually tells you what to do about it, something the platforms have not built well yet. Paradigm is making a direct run at that exception. Hotspots instead of dashboards. Workflows framed explicitly as what used to be a $30,000, six-week consulting engagement. A maturity model benchmarked against 700 companies instead of a chart that stops at “here’s your engagement score.” If it works, Surface could emerge as one of the providers of the outcome-connected layer that made the analytics category irrelevant on its own terms, which is exactly the pattern I’m tracking across every closing window in this series, not just this one.
What I’m Not Sold On Yet
Provocative isn’t the same as proven, and I want to be straight about where this thesis is still unproven.
Paradigm has zero case studies connecting Surface to business performance outcomes, and Joelle told me directly that connective tissue takes at least a year to build credibly. She’s not going to fake it in the meantime. Seventy customers on the platform is real traction, but it’s existing clients migrated at their existing price, not yet net-new proof that the market will pay for this from a cold start. Her own words on the timeline: “I think we have a pretty narrow window to do an excellent job at this.” She’s not wrong, and she knows it better than I do. The bar for reliability in this category is also unforgiving in a way most software categories aren’t: a wrong analysis or a hallucinated data point in a people-strategy recommendation isn’t a minor UX miss, it’s the kind of error that undermines the exact trust Paradigm is banking on as its moat. Joelle acknowledged as much: accuracy is a stated, ongoing engineering priority, not a solved problem.
There’s still room to grow: Paradigm’s biggest inbound request right now is opening the agent to every HR business partner, not just the CHRO’s inner circle, and building role-based permissioning to do that safely is their next unlock. It’s less a gap than a clear signal of where demand is already pulling the product.
None of that undercuts the thesis. It’s exactly what you’d expect to see from a company six months into an AI-native rebuild with a narrow window and no interest in overselling itself. It just means the expertise-as-moat argument is still a bet, not yet a result.
What This Means for the Rest of the Category
If Paradigm’s bet is right, it’s a signal for a much wider set of vendors than people analytics: any services-heavy firm sitting on a pattern library it has never productized should be asking whether its consulting hours are an asset or a liability right now. And it’s a warning for the legacy analytics platforms carrying 2021-era or even earlier tech stacks and 2021-era price points into a buyer conversation that has fundamentally changed shape.
This is one thread in a much bigger map. WorkTech’s Market Windows series has Analytics sitting in the narrow middle of the hourglass right now, and the full category report (buyer behavior, funding data, the vendors making the transformation and the ones running out of time) is coming later in the series, ahead of the State of the Market report dropping October 13. If you want it the day it publishes, subscribe at 1worktech.com/windows.
George LaRocque is the founder of WorkTech, a market intelligence and strategic advisory firm covering the HR and work technology ecosystem. WorkTech tracks global investment, M&A, and tech strategy across 60+ specialized categories. The Q1 2026 Global Work Tech VC Update and Q1 2026 Global Work Tech M&A Update are available at 1worktech.com.
Read more about the Pricing Reckoning facing the entire Work Tech market